Blog
WGU KAM4 C219 Task 2: Business Analysis Report Help, Expert Guide, Tips, and Sample for Healthcare Management Students

Updated on: Aug 23, 2026
| Quick Summary
KAM4 C219 Task 2 requires a board-level Business Analysis Report grounded in six quarters of simulation data. This guide deconstructs every rubric section: strategic thrusts, valuation methodology, financial ratio analysis, cash flow interpretation, and conscious scorecard decisions, with the precision WGU evaluators expect. If you have already completed the simulation and need a passing, rubric-aligned paper, we provide custom-written C219 capstone reports tailored to your actual simulation outputs. |
C219 Task 2 Assignment
Introduction
After completing the business simulation at a competent level (a score above 0.000 for the cumulative total performance at the end of Q6), you will create a written report, using the attached “Business Analysis Template,” for stockholders and the board of directors to review. Analyze the decisions throughout the simulation and evaluate the current state of the business.
Requirements
Your submission must represent your original work and understanding of the course material. Most performance assessment submissions are automatically scanned through the WGU similarity checker. Students are strongly encouraged to wait for the similarity report to generate after uploading their work and then review it to ensure Academic Authenticity guidelines are met before submitting the file for evaluation. See Understanding Similarity Reports for more information.
Grammarly Note:
Professional Communication will be automatically assessed through Grammarly for Education in most performance assessments before a student submits work for evaluation. Students are strongly encouraged to review the Grammarly for Education feedback prior to submitting work for evaluation, as the overall submission will not pass without this aspect passing. See Use Grammarly for Education Effectively for more information.
Microsoft Files Note:
Write your paper in Microsoft Word (.doc or .docx) unless another Microsoft product, or pdf, is specified in the task directions. Tasks may not be submitted as cloud links, such as links to Google Docs, Google Slides, OneDrive, etc. All supporting documentation, such as screenshots and proof of experience, should be collected in a pdf file and submitted separately from the main file. For more information, please see Computer System and Technology Requirements.


What C219 Task 2 Actually Tests, and Why Most Students Struggle
C219 Task 2 is not a standard reflective essay. It is a formal analytical document addressed to a board of directors and an investor audience, built entirely on data your business simulation generated across Q1 through Q6. The distinction matters because WGU evaluators score against a rubric that rewards specificity: you cannot write in generalities about “market conditions” or “strategic alignment” and expect a Competent rating.
The task sits within WGU’s C219 MBA Healthcare Management Capstone (formerly structured as part of the KAM series), and it tests whether you can integrate graduate-level competencies, financial analysis, strategic planning, leadership decision-making, in one cohesive deliverable. The evaluation criteria under Competency 981.1.8 explicitly requires integration across your degree program, meaning evaluators are reading for command of the subject, not just compliance with formatting.
Three patterns consistently push students to Approaching Competence rather than Competent:
- Selecting strategic thrusts that were not documented in Q6 > Strategic Planning > Goals and Strategy, making the connection to business decisions unverifiable.
- Using a valuation methodology without disclosing the assumptions, resulting in a calculation that evaluators cannot reproduce or validate.
- Treating the conscious scorecard section as a summary of what happened rather than a causal analysis of how decisions drove measurable outcomes.
This guide addresses each section of the rubric with the same rigor the task demands, and works better as a planning reference than as a c219 task 2 pdf you skim once and set aside.
C219 Task 1, C219 Task 2, and C219 Task 3: How the Capstone Sequence Fits Together
Before diving into Task 2 itself, it helps to see where it sits in the broader c219 capstone sequence:
- C219 Task 1 establishes the simulation setup and early-quarter strategic decisions. Some students also work from a wgu c219 task 1 powerpoint deliverable at this stage, depending on how the course packages the assignment in a given term.
- C219 Task 2 (also referred to as wgu c219 task 2 or c219 wgu task 2), the subject of this guide, is the board-level Business Analysis Report covering Q1 through Q6 of the simulation.
- C219 Task 3 (c219 wgu task 3) generally builds on the analysis completed in Task 2, so a rubric-aligned, well-documented c219 capstone task 2 report makes Task 3 considerably easier to write.
If you’re mapping out the whole capstone timeline, treat c219 task 1, this task, and c219 task 3 as one continuous data trail rather than three unrelated assignments, since the simulation exports you generate for Task 2 typically carry forward.
A1: Corporate Strategic Thrusts, How to Write the Connection Correctly
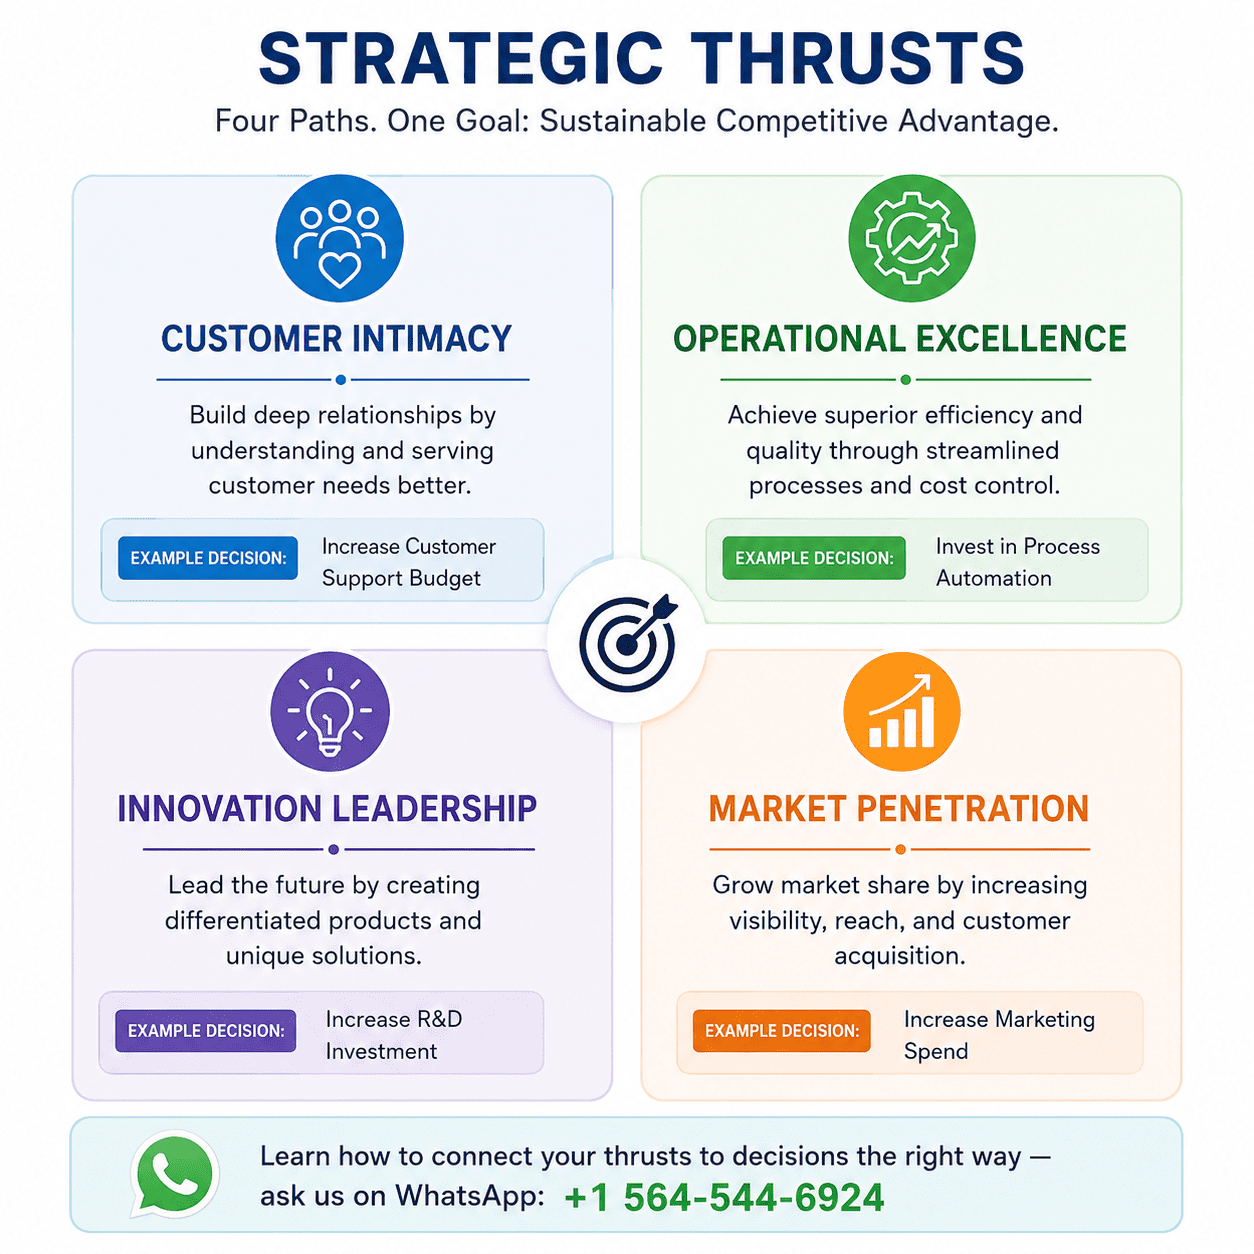
The rubric for A1 is precise: four strategic thrusts selected from the simulation, each linked to one distinct business decision, with an explanation of the causal relationship between them. The most common failure at this section is treating thrusts and decisions as interchangeable, listing what you did without articulating why the thrust directed that specific choice.
A strategic thrust is a directional commitment: growth through innovation, operational efficiency, customer-focused differentiation, market expansion. A business decision is a discrete, simulation-documented action: a pricing change in Q3, a specific R&D investment in Q4, a headcount decision in Q2. The explanation must connect the two with directional logic, not correlation.
Rubric-Compliant Structure for Each Thrust Entry (Task Matrix Example)
The table below works as a practical task matrix example, one row per required component, that you can reuse as a planning template for each of your four thrust entries.
| Component | What WGU Evaluators Expect |
|---|---|
| Strategic Thrust | Exact wording from Q6 > Strategic Planning > Goals and Strategy |
| Business Decision | A specific, simulation-traceable action with quarter reference |
| Causal Explanation | Why the thrust logically necessitated or shaped that decision, not a description of both in isolation |
| Distinction Test | Each of the four decisions must be clearly differentiated from the others in subject matter |
A well-constructed A1 entry reads analytically, not narratively. It does not say “We focused on growth, and we expanded into new markets.” It says: “The Customer Intimacy thrust, adopted in Q4, directed the Q5 decision to reduce average selling price in the premium segment by 8%, prioritizing market penetration over margin in order to capture first-mover positioning ahead of competitor entries flagged in the simulation’s market intelligence reports.”
That level of specificity, quarter reference, percentage, strategic rationale, competitive context, is what separates a Competent submission from one that reads like a summary.
A2: Beneficial Decisions and What You Would Change
A2 splits into two parts with distinct analytical demands. Part A2a asks you to demonstrate that you understand causality, that you can trace a decision to a measurable positive outcome with evidence from the simulation. Part A2b asks you to demonstrate managerial maturity: the ability to diagnose a decision’s failure mode and prescribe a specific corrective action.
A2a: Writing the Beneficial Decision Analysis
The rubric requires “specific examples of benefits that resulted from your decisions.” Vague language, “this decision improved our profitability,” will earn Approaching Competence. What evaluators want is the financial or market trace: which quarter, which metric moved, by how much. If a workforce investment in Q2 reduced employee turnover shown on the conscious scorecard, say so explicitly. If a Q3 product line expansion drove the sales growth reflected in your Q4 balanced scorecard, cite the data.
The conscious scorecard and balanced scorecard exports required in Part B are not incidental attachments, they are the evidence base for A2. Students who treat them as formalities lose the analytical thread the rubric rewards.
A2b: Writing the Decision You Would Change
This is not an apology section. Evaluators are not looking for contrition, they are assessing whether you can engage in executive-level post-mortem analysis. The structure should be: (1) identify the specific decision and the quarter it was made, (2) describe the outcome it produced using simulation data, (3) articulate the alternative decision with enough specificity that a reader could evaluate it as a real strategic choice, and (4) project the likely outcome of the alternative based on the simulation’s mechanics.
A weak A2b entry says: “I would have invested more in marketing earlier.” A competent entry says: “The Q2 decision to hold marketing spend at 12% of revenue, while prioritizing operational capacity, resulted in a 6.3-point market share deficit versus the industry leader by Q4 that proved structurally difficult to recover in the final two quarters. Reallocating 5 percentage points of operational budget to demand generation in Q2, when unit economics were most favorable and competitor ad spend was at its cyclical low, would likely have produced a materially different market position entering the back half of the simulation.”
A3: Valuation and ROI, the Section Most Students Get Wrong

The valuation section is where technically capable students often stumble, not because the math is complex, but because the rubric requires transparent methodology disclosure. You must explain the method, show the calculation, justify your assumptions, and identify the financial data inputs. An answer that presents only a final number, even if mathematically correct, will not pass.
Choosing a Valuation Methodology
WGU’s “Preparing for Task 2” guidance within C219 identifies several accepted approaches. The most commonly applied for simulation-based companies are:
- Price-to-Earnings (P/E) Multiple: Apply an industry-relevant P/E ratio to your Q6 net income. This method is appropriate when the company is profitable, and requires you to justify your chosen multiple with reference to healthcare industry benchmarks.
- Discounted Cash Flow (DCF): Project future free cash flows using your Q6 operating cash flow as a base, apply a discount rate (WACC or a reasoned rate assumption), and sum the present value. This method is more defensible for a graduate-level audience but demands explicit assumption disclosure.
- Asset-Based Approach: Use Q6 total assets minus total liabilities from the balance sheet. This is the most straightforward but tends to undervalue going-concern businesses; if you use it, acknowledge its limitations relative to income-based approaches.
EVALUATOR NOTE The rubric states the valuation must be “accurately calculated,” but accuracy here includes methodological coherence, not just arithmetic. A correct calculation built on an undisclosed or implausible assumption (such as applying a 50x P/E multiple without justification) will not satisfy the “rationale for assumptions” requirement.
A3b: Calculating ROI
The ROI calculation must use the valuation figure from A3a as its base. The standard formula applied in this context is:
ROI = (Current Valuation – Initial Investment) / Initial Investment x 100
The “initial investment” is the starting capital provided to your simulated company at the beginning of the simulation. This figure is documented in the simulation and should be cited directly. Do not approximate or substitute a different figure, evaluators will check the correspondence between your cited inputs and the simulation exports submitted in Part B.
A3c: Implications for Investors
This sub-section is frequently underwritten. Students who calculate a positive ROI and write “this is a good investment” have not met the competency bar. A rigorous investor implications analysis contextualizes the ROI against the risk profile of the simulated company, the capital structure shown on the Q6 balance sheet, the competitive position evidenced by the balanced scorecard, and the sustainability of the cash flows underlying the valuation. If the ROI is modest, discuss what conditions would be required to improve it. If it is strong, assess whether it is reproducible or a function of simulation-specific decisions that would not transfer to a real-world environment.
A4: Financial Performance Analysis, Ratios, Cash Flow, and the Conscious Scorecard
Section A4 is the most data-intensive portion of the report and rewards students who understand what financial metrics actually communicate, not just how to calculate them. The rubric requires one metric per ratio category, cash flow analysis across all four statement categories, and a causal analysis of three conscious scorecard decisions.
A4a: Ratio Analysis with Industry Benchmarks
The four required categories and their simulation locations:
| Ratio Category | Simulation Location | Industry Benchmark Source |
|---|---|---|
| Liquidity | Q7 Ratio Tab | Industry Financial Ratios Tab (same simulation) |
| Activity | Q7 Ratio Tab | Industry Financial Ratios Tab |
| Leverage | Q7 Ratio Tab | Industry Financial Ratios Tab |
| Profitability | Q7 Ratio Tab | Industry Financial Ratios Tab |
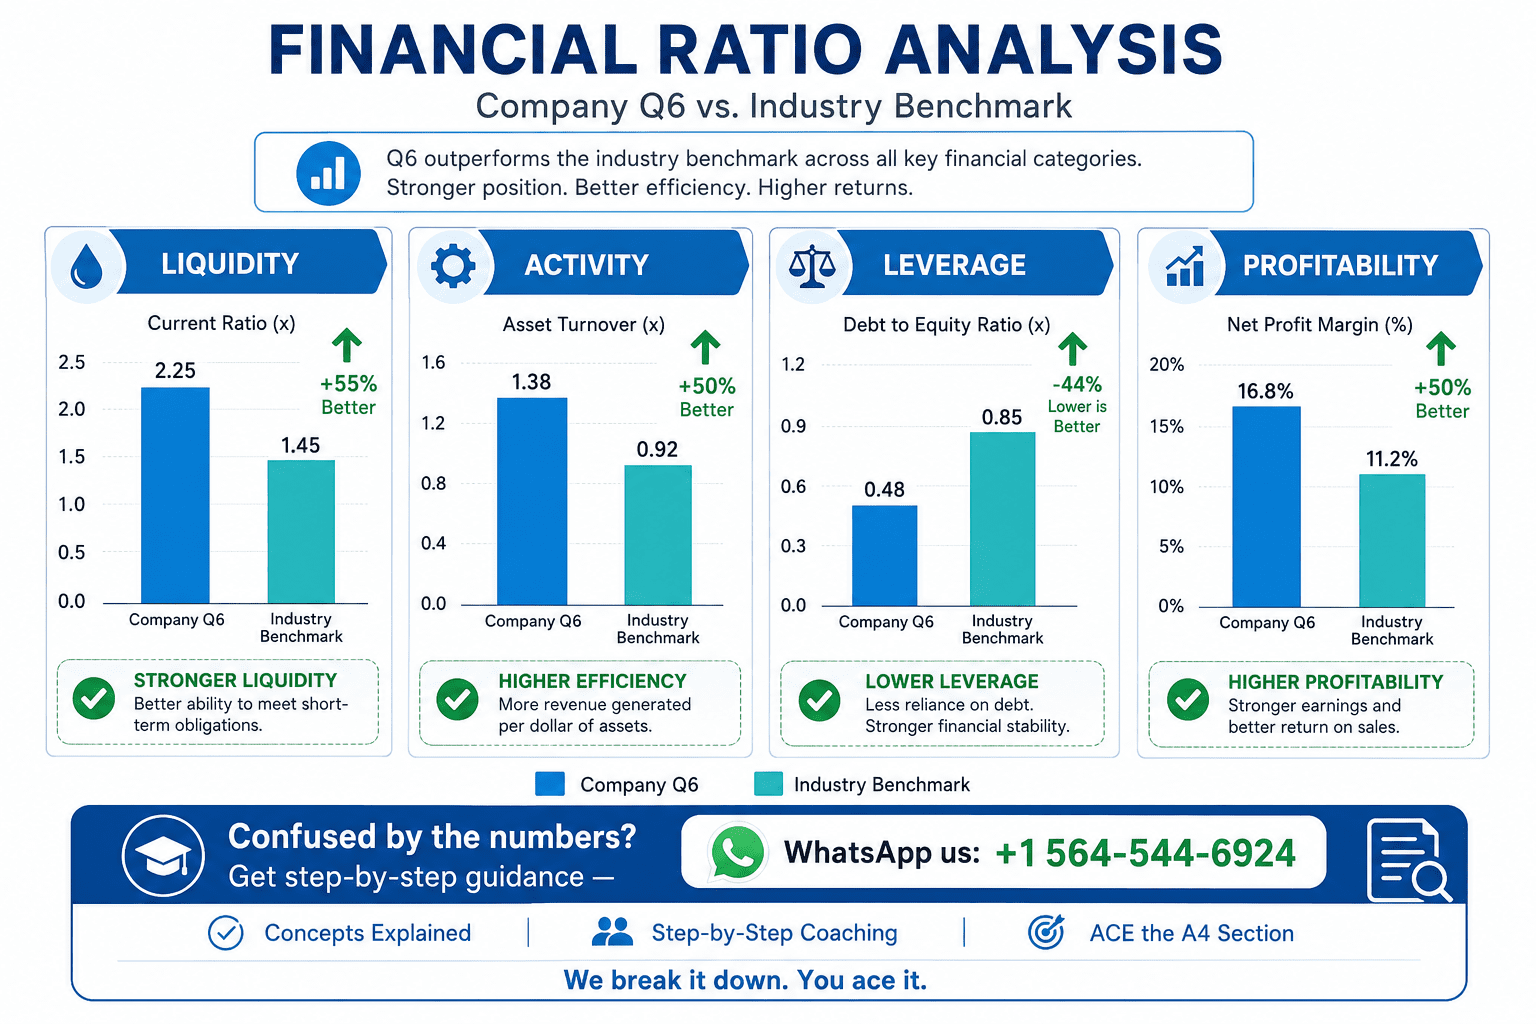
Each ratio entry in your report must include three elements: the Q6 figure for your company, the industry benchmark figure, and an interpretive statement that addresses what the comparison reveals about your company’s financial health. The interpretive statement is not optional, the rubric explicitly tests whether your analysis “addresses what the Q6 ratio numbers indicate about the company’s financial performance.”
For example, a Current Ratio of 2.1 against an industry benchmark of 1.4 indicates strong short-term liquidity, your company holds significantly more current assets relative to current liabilities than the industry average, suggesting conservative working capital management. But a current ratio that high may also indicate underdeployment of liquid assets, a trade-off worth noting if your profitability ratios show below-benchmark returns.
A4b & A4c: Cash Flow Analysis
The four cash flow categories required by the rubric map directly to your Q6 cash flow statement export:
- Cash Balances: Opening and closing cash position, with the net change as a measure of overall liquidity trajectory.
- Operating Activities: Cash generated by core business operations, the most important indicator of sustainable financial performance. A growing company with negative operating cash flow is funding growth through financing, which carries compounding risk.
- Investing Activities: Capital deployed in assets and equipment. Sustained negative investing cash flow is expected in growth phases; positive investing cash flow may signal asset liquidation.
- Financing Activities: Debt issuance, repayment, or equity transactions. The direction and magnitude of financing cash flows should be read in conjunction with your leverage ratio to assess capital structure risk.
The A4c question, what do these activities reveal about overall company health, is a synthesis question. It does not ask you to re-describe each category. It asks you to interpret the pattern: is the company generating sufficient operating cash to fund investment without over-relying on financing? Is the cash balance trajectory sustainable into future quarters? That integrative analysis is what earns the Competent rating.
A4d: Conscious Scorecard Decisions
Three decisions from the conscious scorecard, each with a causal link to company performance. The conscious scorecard measures dimensions beyond financial returns: employee satisfaction, environmental impact, supplier relationships, community investment. Students frequently write this section as a description of what the scorecard shows rather than an analysis of how the decisions that shaped those scores affected business outcomes.
A strong A4d entry identifies the specific decision, locates it on the scorecard, traces its effect through to a measurable performance outcome (financial or operational), and acknowledges any trade-off involved. A decision to cut employee development spending, for example, may improve short-term operating cash flow while depressing the employee satisfaction score, and a thoughtful analysis notes both directions of that trade-off.
Approaching Competence vs. Competent: What the Difference Actually Looks Like
| Rubric Section | Approaching Competence | Competent |
|---|---|---|
| A1 Strategic Thrusts | Lists thrusts and decisions but describes them separately without causal linkage | Each thrust explicitly shapes the decision, the “why” is documented with simulation specifics |
| A2a Beneficial Decisions | States that a decision was positive without tracing it to a measurable outcome | Cites specific metric movements (market share %, margin change) tied to the decision and quarter |
| A2b Would-Change Decisions | Acknowledges a decision did not work well and proposes a vague alternative | Names the decision, the outcome it produced with data, and a specific alternative with projected rationale |
| A3a Valuation | Presents a final valuation figure without disclosing methodology or assumptions | Full method, calculation, assumption rationale, and input data are all present |
| A3b ROI | ROI calculated with a different base than A3a valuation | ROI explicitly uses the A3a valuation as the base, calculation shown step by step |
| A4a Ratios | Calculates ratios but does not compare against industry benchmarks or interpret the comparison | Each ratio is compared to the industry benchmark with an interpretive statement about what the gap reveals |
| A4c Cash Flow Health | Summarizes each cash flow category again without integrative analysis | Synthesizes the four categories into a coherent assessment of the company’s financial trajectory |
Part B: Required Simulation Exports, What to Submit and How
Part B is binary in the rubric, either the required reports are submitted or they are not. There is no Approaching Competence rating, only Competent or Not Evident. The required exports are:
- The cumulative balanced scorecard with a positive cumulative total performance score at the end of Q6. If your score is negative, the task cannot be submitted, the requirement to complete the simulation at a competent level is a prerequisite, not a guideline.
- The conscious scorecard report.
- Income statement, balance sheet, and cash flow statement, all from Q6 as exported from Q7 of the simulation.
These documents should be submitted as separate PDF attachments, clearly labeled. Errors in this section, submitting Q5 data, submitting incomplete exports, or failing to include all three financial statements, are entirely avoidable and represent lost points on a binary rubric item.
Frequently Asked Questions: WGU C219 Task 2
Is C219 Task 2 the same as C216 Task 2?
Structurally similar, but not identical. C219 (Healthcare Management) and C216 (MBA Capstone) use the same Marketplace Simulations platform and share overlapping rubric elements. However, the strategic context, industry benchmarks, and conscious scorecard dimensions may differ. Content written for C216 should not be submitted for C219 without review against the C219-specific rubric.
How long should the C219 Task 2 Business Analysis Report be?
There is no mandated page count. However, given that the rubric requires specific data, calculations with disclosed assumptions, ratio analysis with industry comparisons, and causal narrative across multiple sections, a thorough submission typically runs 10 to 15 pages, excluding the Q6 simulation export attachments. Shorter submissions are not automatically penalized, but they are statistically more likely to lack the specificity the rubric rewards.
What valuation methodology does WGU expect for C219 Task 2?
WGU does not prescribe a single method, the rubric rewards correct application and full disclosure of whatever method you choose. The most defensible approaches are P/E multiple (requires industry benchmark justification), DCF (requires discount rate assumption disclosure), and asset-based (simplest, but acknowledge its limitations). The calculation, the inputs, and the rationale for assumptions are all separately evaluated.
Can I pass C219 Task 2 if my simulation score was low?
The prerequisite is a cumulative total performance score above 0.000 at the end of Q6. If your score meets that threshold, you can submit Task 2 regardless of how low the score is. The analytical quality of your report is evaluated independently of your simulation performance level. In fact, a low simulation score often produces richer A2b material, the decisions you would change are more apparent when outcomes were suboptimal.
What is the conscious scorecard in the WGU business simulation?
The conscious scorecard tracks non-financial performance dimensions, employee satisfaction, environmental sustainability, supplier ethics, and community investment, across the simulation quarters. It operates in parallel with the balanced scorecard and is designed to reflect the “conscious capitalism” framework embedded in the WGU MBA curriculum. For C219 Task 2, you are required to select three decisions reflected on the conscious scorecard and analyze how each affected company performance, financial or operational.
Is there a good C219 Task 2 Reddit thread to check before I start?
Searching c219 task 2 reddit or wgu c219 task 2 reddit will surface threads where students compare turnaround times, share general impressions of the workload, and occasionally post a redacted c219 task 2 sample section for feedback. Treat those threads as a gauge of difficulty and pacing, not as a source of rubric guidance, individual simulation data varies enough between students that another person’s numbers won’t map onto your report, and posting or copying someone else’s submitted work would raise the same originality concerns as any other unauthorized submission.
Where can I find a reliable C219 Task 2 sample or example?
A genuinely useful c219 task 2 example shows you the structure of a strong A1 through A4 entry, not a set of numbers to copy. This guide’s rubric-compliant tables function as a task matrix example you can fill in with your own simulation figures. Because every student’s Q1 through Q6 decisions and outputs differ, a c219 task 2 sample built on someone else’s data will not hold up against your evaluator’s rubric checks, the specificity requirement is exactly what a copied sample cannot satisfy.
Need a Custom C219 Task 2 Business Analysis Report Written to Your Simulation Data?
Every student who completes the WGU business simulation has a unique data set: different quarterly decisions, different balanced scorecard outputs, different financial ratios. A generic template or a recycled sample paper will not reflect your simulation results and will not satisfy rubric requirements that demand specificity.
Gradevia.com writes custom C219 Task 2 Business Analysis Reports built around your actual Q6 simulation data. Our writers are familiar with the WGU C219 rubric, the Marketplace Simulations platform mechanics, APA 7 formatting standards, and the level of analytical specificity that earns Competent ratings. Every submission is original, Grammarly-reviewed, and structured to address each rubric criterion precisely.
WHAT WE PROVIDE Full C219 Task 2 Business Analysis Report, rubric-aligned across all A1-A4 sections, valuation methodology with disclosed assumptions, financial ratio analysis with industry benchmark comparisons, cash flow synthesis, conscious scorecard decision analysis, APA 7 in-text citations and reference list, Grammarly-clean professional writing, delivered in Word (.docx) format ready for WGU submission.
Message us on WhatsApp at +1 (564) 544-6924 to get started with your C219 capstone Task 2 report.